TL;DR: The Fed just raised its benchmark rate a quarter point, but that's not the same thing as your mortgage rate. Local data shows the Grand Strand sitting in a balanced market, not a crash, so the real question for buyers and sellers isn't "should I panic" — it's "does this fit my own numbers."
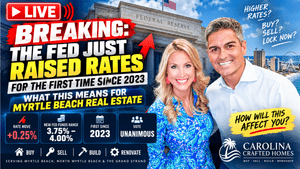
Myrtle Beach real estate agents Frank and Tiffany Hereda of Carolina Crafted Homes opened this week's livestream with news that had a lot of people asking questions: the Federal Reserve raised its benchmark rate a quarter point this week, and mortgage rates are sitting in the high 6% to low 7% range depending on the loan program. For anyone watching the Grand Strand housing market, the instinct is to wonder whether this is 2008 all over again. It isn't. Single-family months of supply on the Grand Strand sat at 4.2 in July 2026, a figure the Coastal Carolinas Association of REALTORS® (CCAR MLS, July 2026) classifies as a fairly balanced market — not a buyer's market, not a seller's market. This post breaks down what the Fed rate hike actually changes, what current data says about local conditions, and how buyers and sellers are actually responding.
Fed Rate Hike vs. Mortgage Rates: What Actually Changed
A lot of confusion this week centered on one basic distinction Frank and Tiffany made early in their livestream: the Federal Reserve's rate and a mortgage rate are not the same thing. The Fed rate is what the Federal Reserve charges banks to borrow money overnight; it moved from 3.75% to 4.00% this week. A mortgage rate is priced off a different benchmark — largely the 10-year Treasury yield — and moves on its own timeline. Frank and Tiffany reported current 30-year rates sitting around 6.95%, with jumbo loans running higher, closer to 7.22%.
That distinction matters for anyone thinking a Fed move will instantly change what they qualify for. It doesn't work that way. Rate movement tends to trickle through gradually, and according to the Coastal Carolinas Association of REALTORS® 2025 Annual Report, mortgage rates declined through the second half of 2025 and are expected to stay in the 6% range through the year ahead. That's the backdrop this Fed decision landed on — not a market moving from cheap money to expensive money overnight, but a market that's been living in the 6s and 7s for a while now.
Is the Myrtle Beach Housing Market Crashing? What the Numbers Say
Rate headlines tend to trigger the same question: is this the start of another 2008. The honest answer, based on current data, is no — and the difference comes down to what's actually stressing the market this time. In 2008, lending standards had collapsed; low- and no-documentation loans were common, and buyers had little equity cushion. That isn't the current setup.
| Property Type | Months of Supply (July 2026) | Year-over-Year Change |
|---|---|---|
| Single-Family | 4.2 | - 4.5% |
| Condo/Townhouse | 7.6 | - 5.0% |
Single-family months of supply actually eased slightly from the year before, landing at 4.2 — a figure most agents would call a balanced market rather than a buyer's or seller's market. Condo supply runs higher at 7.6 months, reflecting more competition among sellers in that segment specifically. Grand Strand single-family homes also carried a median 130 days on market in Myrtle Beach proper as of July 2026, per CCAR's Local Market Update, up modestly from the year before but nowhere near the freeze that defined 2008-2009. The takeaway Frank and Tiffany kept returning to on the livestream: real estate conditions are hyper-local. A statewide or national headline about rates doesn't tell you what's happening on a specific street in Carolina Forest or North Myrtle Beach.
Should You Wait for Rates to Drop Before Buying in Myrtle Beach?
This is the question underneath almost every rate headline, and it doesn't have a one-size answer. According to the National Association of REALTORS®' 2025 Profile of Home Buyers and Sellers, 74% of all buyers financed their purchase, and 62% of those buyers chose a fixed-rate mortgage — meaning most people locking in today's rate are doing so with the expectation of refinancing later if rates fall, not staying at today's number forever. That's the logic behind the old real estate phrase Frank and Tiffany referenced: marry the house, date the rate.
Waiting carries its own cost. If a meaningful share of sidelined buyers jump back into the market once rates drop, increased competition tends to push prices up, which can offset — or exceed — the monthly savings from a lower rate. NAR's February 2026 Realtors Confidence Index shows first-time buyers already made up 34% of February sales, up from 31% the month before, suggesting some buyers are choosing to move now rather than wait. Buyers weighing this decision should run their own numbers with a licensed lender rather than trying to time a market that, historically, very few people time correctly.
Builder Incentives Are Reshaping Local Competition
One shift worth watching locally: builders offering rate buydowns and closing cost assistance are creating real competition for resale inventory. When a builder can offer a buyer a lower effective rate on new construction, that buyer's purchasing power increases — sometimes enough to afford a larger home than they expected. That dynamic is putting pressure on resale sellers, who don't have the same tools to offer, and it's one more reason pricing a home realistically from day one matters more than ever in this stage of the market.
For anyone building or buying new construction in the Myrtle Beach area, it's worth asking directly what rate promotions or closing cost credits a builder is currently offering, since these vary and typically apply only to specific loan types.
If you've been sitting on the fence wondering whether this is the right window to buy, build, or list in the Myrtle Beach area, we're happy to walk through your specific numbers and timeline — get in touch and we'll help you figure out what actually makes sense for your situation.
FAQ Section
Is the Fed rate the same as my mortgage rate?
No. The Fed rate is what the Federal Reserve charges banks for overnight borrowing; it moved to 4.00% this week. Mortgage rates track more closely with the 10-year Treasury yield and move on their own schedule, often with a delay. According to the Coastal Carolinas Association of REALTORS®' 2025 Annual Report, mortgage rates are expected to stay in the 6% range through the year ahead, regardless of individual Fed moves.
Is the Myrtle Beach housing market going to crash?
Current data doesn't point that direction. Single-family months of supply sat at 4.2 in July 2026, per CCAR MLS — generally considered a balanced market. The lending conditions that caused the 2008 crash, such as widespread no-documentation loans and minimal buyer equity, aren't present in today's market.
Should I wait for mortgage rates to drop before buying?
That depends on your personal finances and timeline more than the headlines. Waiting can mean facing more buyer competition and rising prices later if rates do fall, potentially offsetting any savings. A licensed lender can run your specific numbers against different rate and timing scenarios.
Do builders' rate buydowns actually help buyers?
Yes, in many cases. A builder-subsidized rate buydown can increase what a buyer can afford, sometimes enough to move into a larger home or different community. Terms vary by builder and loan program, so ask directly what's currently being offered and whether it applies to your loan type.
How many months of supply is considered a balanced market?
Most agents consider four to six months of supply a balanced market — not strongly favoring buyers or sellers. The Grand Strand's single-family supply of 4.2 months as of July 2026 falls within that range, per CCAR MLS data.
What does "marry the house, date the rate" mean?
It's shorthand for buying a home you love now at the current rate, with the plan to refinance later if rates drop. It only makes sense if you can comfortably afford the current payment regardless of whether rates ever fall — consult a licensed lender before assuming a future refinance.
Sources
Coastal Carolinas Association of REALTORS® MLS (Monthly Indicators, July 2026): https://www.ccarsc.org/pages/marketstats/
Coastal Carolinas Association of REALTORS® 2025 Annual Report on the Coastal Carolinas Housing Market: https://www.ccarsc.org/pages/marketstats/
National Association of REALTORS® 2025 Profile of Home Buyers and Sellers: https://www.nar.realtor/
National Association of REALTORS® February 2026 Realtors Confidence Index Survey: https://www.nar.realtor/
Why Waiting for Rates to Drop Could Cost Buyers More: https://www.carolinacraftedhomes.com/blog/waiting-for-rates-to-drop-costs-buyers-2026