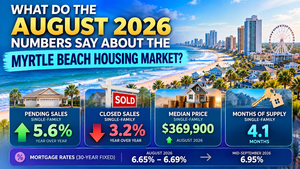
TL;DR: Grand Strand prices moved in two directions this year. The regional single-family median edged up while condo medians slipped, and condo supply runs well above single-family supply. Before you offer on a vacation home, confirm the jurisdiction’s rental rules, the flood zone, insurance costs and the total carrying cost at today’s mortgage rates.
The Grand Strand market split in 2026. According to CCAR MLS (September 2026), the region’s single-family median rose 1.4% year over year to $370,000. The condo median fell 5.0% to $230,125 over the same period.
That split matters if you’re shopping for a vacation home in Myrtle Beach. Condos now carry about 7.5 months of supply, compared with 4.2 months for single-family homes, per CCAR’s Housing Supply Overview (September 2026). Meanwhile, FRED data shows the 30-year fixed rate at 6.95% for the week of September 17, 2026, up from 6.26% a year earlier.
This guide covers what a beach house purchase in South Carolina costs today, how rental rules vary by location and what to verify before you write an offer.
What a Vacation Home in Myrtle Beach Costs in 2026
Price depends heavily on location and property type. Coastal ZIP codes show a wide spread, and the gap between condos and detached homes is large.
The table below shows August 2026 medians for five Grand Strand coastal areas.
Median Sales Price by Coastal Area — September 2026
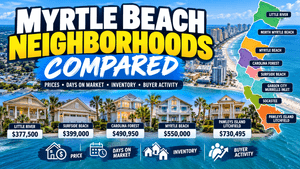
| Area (ZIP) | Single-Family Median | Townhouse/Condo Median | Condo Inventory |
|---|---|---|---|
| Myrtle Beach (29572, 29577) | $488,000 | $177,450 | 1,470 |
| North Myrtle Beach (29582) | $562,500 | $280,000 | 637 |
| Garden City / Murrells Inlet (29576) | $510,000 | $300,000 | 199 |
| Surfside Beach (29575) | $375,000 | $182,000 | 173 |
| Little River (29566) | $365,100 | $215,000 | 233 |
Source: CCAR MLS Local Market Update (September 2026). Medians do not account for sale concessions. Single-month figures can swing sharply on small sample sizes, so year-to-date figures give a steadier read.
A few patterns stand out:
Myrtle Beach condos softened. The year-to-date condo median in 29572 and 29577 fell 10.9% to $205,000 through September 2026, according to CCAR MLS.
Condo inventory is deep. Those two ZIP codes held 1,470 condos for sale in September, up 4.1% from a year earlier.
North Myrtle Beach held firm. Its year-to-date condo median rose 5.1% to $310,000.
Detached homes look steadier on a year-to-date basis. The Myrtle Beach single-family median sat at $522,500 through September, down 1.4%, while single-family inventory rose 17.1% to 343 homes, per CCAR MLS (September 2026). More listings give buyers more options to compare.
Rental Rules Depend on Where the Property Sits
Many buyers plan to rent out their beach house part of the year. Whether you can do that legally depends on jurisdiction, not just the listing description.
The Grand Strand includes several separate governments. The City of Myrtle Beach, North Myrtle Beach, Surfside Beach and unincorporated Horry County each set their own zoning and rental rules. A Myrtle Beach mailing address does not guarantee the property sits inside city limits.
Before you offer, confirm these points:
Which government has jurisdiction over the parcel
Whether short-term rentals are allowed in that specific zoning district
What HOA or condo regime documents say about rental terms, minimum stays and registration
What business licensing and local taxes apply to rental income
HOA and regime rules can be stricter than local zoning. Read them before your inspection period ends, not after.
For a deeper look at local zoning, see our guide on short-term rental rules in Myrtle Beach. Rules change often, so verify current ordinances with the relevant government office. Consult with a licensed professional for your specific situation.
Rental income also isn’t guaranteed. Location, season and property type all shape occupancy. Our post on short-term rental income in Myrtle Beach walks through what drives those numbers.
What to Check Before You Offer on a Beach House
A beach house purchase in South Carolina comes with checks that inland buyers rarely face. Here’s where to focus.
Flood zone and elevation. In unincorporated Horry County, new buildings in AE flood zones must sit at least 3 feet above base flood elevation, according to Horry County Government. In VE zones, that 3-foot standard applies to the lowest horizontal structural member. Ask for the property’s elevation certificate early.
Substantial improvement rules. The National Flood Insurance Program applies a 50% rule. If improvements or repairs equal or exceed 50% of the building’s market value, the structure must meet new-construction standards, per Horry County Government. That can change renovation budgets quickly.
Insurance costs. Coastal coverage can shift your carrying costs more than the mortgage rate does. Get quotes for wind, flood and liability coverage before your inspection period ends. Our guide to homeowners insurance in coastal SC covers the basics.
Seller residency. Many Grand Strand sellers live out of state. Under South Carolina rules, anyone paying a nonresident seller for real property must withhold tax on the sale, according to SCDOR Form I-290 (rev. July 2023). Your closing attorney typically handles this, but plan for it in your timeline.
Financing math. At 6.95% as of September 2026 (FRED), the rate you lock will shape your monthly cost. Rates and programs are subject to change; verify current details with your lender.
How Vacation Home Buyers Compare Nationally
Vacation buyers make up a small share of the national market. The NAR REALTORS® Confidence Index (February 2026) found that 5% of sales were intended for vacation use. Non-primary residence purchases, including rentals, made up 16% of sales.
Cash plays a large role. According to the same NAR survey, 31% of February 2026 sales were all-cash. The NAR Profile of Home Buyers and Sellers (2025) put all-cash buyers at 26%, which NAR describes as continuing a record high.
Among recent buyers, 4% also owned one or more vacation homes, per the NAR Profile (2025).
Locally, the market gives buyers more room to evaluate. Single-family homes in the CCAR region spent a median 118 days on market in September 2026, and condos spent 137 days, according to CCAR MLS. Sellers received about 97.3% of list price for single-family homes.
Those numbers point to a measured pace. Buyers generally have time to complete inspections, review HOA documents and compare oceanfront and second-row options. Our breakdown of second-row vs. oceanfront stays explains how that location choice affects price and use.
Choosing between a Myrtle Beach condo and a detached home in North Myrtle Beach or Surfside Beach changes nearly every number above, from price to flood elevation to rental eligibility. If you’re weighing those options or wondering whether building fits your plans better than buying, our team can walk through the local details with you. Start the conversation whenever you’re ready.
FAQ
How much does a vacation home in Myrtle Beach cost?
It depends on property type and location. According to CCAR MLS (September 2026), the year-to-date single-family median in Myrtle Beach ZIP codes 29572 and 29577 was $522,500, while the townhouse/condo median was $205,000. North Myrtle Beach ran higher, at $569,995 for single-family homes and $310,000 for condos. Surfside Beach and Little River came in lower for detached homes. Single-month medians can swing on small sample sizes, so year-to-date figures for your target area give a more reliable picture.
Is it better to buy a condo or a house as a beach vacation home?
Each has trade-offs. Condos offer a lower entry price, but supply is deeper. The CCAR region held about 7.5 months of condo inventory versus 4.2 months for single-family homes, per the Housing Supply Overview (September 2026). Condos also come with regime fees and rental rules set by the association. Detached homes cost more upfront but give you more control over use and improvements. Compare total carrying costs, not just purchase price.
Can I rent out my Myrtle Beach vacation home?
Possibly, but it depends on jurisdiction, zoning and HOA rules. The City of Myrtle Beach, North Myrtle Beach, Surfside Beach and unincorporated Horry County each regulate rentals separately. Condo regime documents may add their own limits on minimum stays or registration. Confirm the parcel’s jurisdiction and read the governing documents before your inspection period ends. Rules change, so verify current ordinances directly with the local government office and consult with a licensed professional for your specific situation.
What flood rules apply to a beach house in Horry County?
In unincorporated Horry County, new buildings in AE flood zones must have the lowest floor at least 3 feet above base flood elevation, according to Horry County Government. In VE zones, that standard applies to the lowest horizontal structural member. The National Flood Insurance Program also applies a 50% rule: if improvements or repairs reach half of the building’s market value, the structure must meet new-construction standards. Request the elevation certificate early in your search.
What are mortgage rates for a vacation home right now?
FRED data shows the 30-year fixed-rate average at 6.95% for the week of September 17, 2026, up from 6.26% a year earlier. That figure is a national average for conventional loans and doesn’t reflect second-home pricing, which can differ by lender and loan program. Get quotes specific to a second-home purchase before you set your budget. Rates and programs are subject to change; verify current details with your lender.
What happens if the seller lives out of state?
South Carolina requires anyone paying a nonresident seller for real property to withhold tax on the sale, according to SCDOR Form I-290 (rev. July 2023). The withholding is reported on Form I-290, and the return and payment are due by the 15th of the month after the sale. In practice, your closing attorney usually handles the paperwork. Ask about it early so it doesn’t delay closing. Consult with a licensed professional for your specific situation.
Sources
CCAR MLS Project Files (Monthly Indicators, Housing Supply Overview — September 2026; Local Market Update — August 2026): https://www.ccarsc.org/pages/marketstats/
FRED Economic Data (30-Year Fixed Rate Mortgage Average, MORTGAGE30US): https://fred.stlouisfed.org/
National Association of REALTORS® (REALTORS® Confidence Index, February 2026; Profile of Home Buyers and Sellers, 2025): https://www.nar.realtor/
Horry County Government — Build Responsibly: https://horrycountysc.gov/
SCDOR — Nonresident Real Estate Withholding (Form I-290): https://dor.sc.gov/forms-site/Forms/I290.pdf
Short-Term Rental Rules in Myrtle Beach: https://www.carolinacraftedhomes.com/blog/short-term-rental-rules-myrtle-beach-2026
Myrtle Beach Short-Term Rental Income: https://www.carolinacraftedhomes.com/blog/myrtle-beach-short-term-rental-income-2026
Can You Airbnb in Myrtle Beach? Zoning Explained: https://www.carolinacraftedhomes.com/blog/can-you-airbnb-in-myrtle-beach-zoning-2026
Second-Row vs. Oceanfront in Myrtle Beach: https://www.carolinacraftedhomes.com/blog/second-row-vs-oceanfront-myrtle-beach-stay-2026
Homeowners Insurance in Coastal SC: https://www.carolinacraftedhomes.com/blog/homeowners-insurance-coastal-sc-2026
Myrtle Beach Real Estate Investing Guide: https://www.carolinacraftedhomes.com/investingguide